If you own a static caravan, holiday lodge, or park home in Northern Ireland, you might assume it’s covered by your regular home insurance policy. It isn’t. Mobile homes are built and sited differently to bricks-and-mortar houses, which means they carry different risks, and need a different type of policy. This guide explains exactly what mobile home insurance in Northern Ireland covers, who needs it, and how to make sure you’re not left exposed.
What Is Mobile Home Insurance?
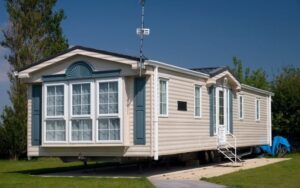
Mobile home insurance is a specialist policy designed to protect static caravans, park homes, and holiday lodges that are permanently sited, as opposed to touring caravans, which are towed on the road. Because your mobile home stays in one place, usually on a caravan park or private site, this type of policy is often described as “static” cover rather than “touring” cover.
It’s important not to confuse the two:
- Mobile home / static caravan insurance — covers a unit that stays on-site year-round or seasonally
- Touring caravan insurance — covers a caravan that’s towed behind a vehicle and includes cover for transit, road risk, and towing accidents
If you only ever tow your caravan to a site once and leave it there, static mobile home cover is what you need.
Is Mobile Home Insurance a Legal Requirement in Northern Ireland?
No, mobile home insurance is not a legal requirement in Northern Ireland. However, it’s strongly recommended, and many caravan parks and holiday sites will require proof of insurance as a condition of your site licence or pitch agreement. Given how much mobile homes and lodges can vary in value, going without cover is a significant financial risk.
What Does Mobile Home Insurance Cover?
While cover varies by insurer and policy level, a typical mobile home insurance policy in Northern Ireland includes protection against:
- Fire — damage caused by fire, including costs for fire brigade call-outs
- Theft and attempted theft — including forced entry and vandalism
- Storm and flood damage — particularly relevant given many mobile homes in Northern Ireland are sited in coastal locations or around Fermanagh’s lakelands
- Accidental damage — cover for unexpected damage to the structure
- Escape of water — including burst pipes caused by freezing conditions over winter
- Contents cover — for furniture, appliances, and personal belongings kept in the unit
- Fixtures and fittings — decking, verandas, sheds, gas cylinders, aerials, and satellite dishes
- Public liability cover — protection if a visitor or guest is injured on your property, with generous limits typically available
- Alternative accommodation costs — if your mobile home becomes uninhabitable during a holiday period due to an insured event
- Removal and repair transport costs — the cost of transporting your unit to a repairer if it can’t be fixed on-site
Some insurers also offer new-for-old replacement, meaning if your mobile home is destroyed or stolen, you receive the cost of a brand-new equivalent rather than just its depreciated market value. This is worth checking carefully, as it can make a significant difference to a claim payout.
What’s Usually Excluded from Mobile Home Insurance?
Standard policies typically won’t cover:
- Short-term rental or Airbnb-style lettings — if you let your mobile home out for payment, you’ll usually need to declare this and may require additional cover, including public liability for paying guests
- Damage from long-term unoccupancy — many policies have restrictions or excess variations if the unit is left empty for more than seven consecutive days
- Frost damage from an undrained water system — most policies expect you to drain the water system over winter (typically between October and March); failing to do so can invalidate a claim
- Negligence — for example, leaving the mobile home unlocked or failing to take reasonable security precautions
Who Needs Mobile Home Insurance?
Mobile home insurance is worth considering if you own:
- A static caravan on a holiday park in Northern Ireland
- A park home or modular home used as a holiday retreat
- A holiday lodge sited on private land or a residential park
- A mobile home you occasionally let out to family, friends, or paying guests
If you’re planning to rent your mobile home out on a regular basis, it’s worth speaking to a broker directly, as this changes your risk profile and the type of cover you’ll need.
Factors That Affect the Cost of Mobile Home Insurance
Several factors influence your premium, including:
- The age, make, and model of your mobile home
- Its location — coastal and low-lying sites carry higher flood risk
- The value of the structure and its contents
- Security features in place, such as alarms, ground anchors, or secure storage
- Your claims history
- Whether the unit is occupied seasonally or year-round
Improving security, for example, installing an alarm, ground anchors, or additional locks, can help reduce your premium, as can choosing a pitch on higher ground where flood risk is lower.
How Dickson & Wilson Insurance Brokers NI Can Help
Every mobile home is different, and so is every owner’s situation, whether you’re insuring a holiday retreat near Fermanagh’s lakelands, a static caravan near the coast, or a park home you occasionally rent out. As an independent broker, we compare cover across a panel of insurers to find a policy that matches how you actually use your mobile home, rather than a one-size-fits-all package.
Get in touch with our team today for a mobile home insurance quote tailored to your needs.
Get a Mobile Home Insurance Quote →
Frequently Asked Questions
Is mobile home insurance the same as caravan insurance? Not quite. Mobile home insurance covers static units that stay in one location, while caravan insurance for touring caravans also includes cover for towing and road transit.
Can I use my regular home insurance for a mobile home? No. Mobile homes are constructed differently to standard houses, so a standard home insurance policy won’t provide adequate cover. You need a specialist mobile home or static caravan policy.
Do I need public liability cover for my mobile home? It’s highly recommended, particularly if friends, family, or paying guests use the property. Public liability cover protects you if someone is injured while staying at your mobile home.
What happens if I don’t drain my water system over winter? If your mobile home is left unoccupied and the water system isn’t drained, any resulting frost or burst pipe damage may not be covered, as most policies require this as a condition of cover.
Does mobile home insurance cover Airbnb-style rentals? Not under a standard policy. If you plan to let your mobile home out for payment, you’ll need to inform your insurer and may require additional cover.